Capital Unlocked: Decoding Kenya’s Mega-Deal Surge and the New Frontier of East African Finance
For most of the past three years, sub-Saharan African capital markets were characterised by risk aversion, macroeconomic volatility, and an extended freeze on primary market listings. Yet over the past six months, Kenya’s financial landscape has seen a dramatic uptick in deal velocity, cross-border M&A, and long-awaited market liquidity.
From Quickmart’s landmark KSh15 billion initial public offering (IPO) and Asahi Group Holdings’ US$2.3 billion acquisition of Diageo’s controlling stake in East African Breweries PLC (EABL), to Access Bank’s acquisition and structural integration of National Bank of Kenya (NBK), and Safaricom’s ongoing corporate balance-sheet optimisation via domestic debt markets, transaction activity in Nairobi is picking up pace.
Is this deal momentum a temporary valuation rebound, or is Kenya establishing a new structural paradigm as East Africa’s pre-eminent financial gateway?
The Deal Anatomy: Private Capital Meets Public Liquidity
The nature of these recent transactions reveals a distinct shift in how capital enters, is rebalanced, and exits within the domestic economy:
- The Retail & PE Exit Test (Quickmart IPO): Selling two billion shares at KSh7.50 to raise KSh15 billion is a decisive test of domestic retail and institutional investor appetite. It offers a crucial public exit for private equity backers while testing whether domestic savings, increasingly accessed through retail investment rails, can absorb large-scale equity listings after years of IPO drought.
- Global Strategic Re-allocation (EABL & Asahi): The US$2.3 billion acquisition of Diageo’s stake in EABL by Japan’s Asahi Group Holdings shows that tier-one East African consumer platforms retain premier enterprise value. Global conglomerates remain willing to deploy massive balance sheets to East African cash-flow powerhouses despite historical FX and inflationary headwinds.
- Banking Consolidation & Scale (NBK & Access Bank): Pan-African financial giants continue to pursue M&A to secure immediate retail and commercial distribution footprints in East Africa, consolidating fragmented assets into larger, balance-sheet-resilient regional lending engines.
- Corporate Debt Market Deepening (Safaricom): Dominant corporate issuers are actively diversifying away from traditional commercial bank credit lines towards debt market instruments and commercial paper, optimising their cost of capital while establishing transparent corporate yield benchmarks.
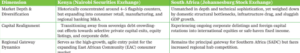
Regional Juxtaposition: Kenya’s NSE vs South Africa’s JSE
To assess whether Kenya is genuinely “coming off the edge”, it is useful to benchmark its current trajectory against Africa’s largest liquidity pool, the Johannesburg Stock Exchange (JSE).
 |
||
|
|
Policy-Driven Structural Shift vs Cyclical Valuation Reset
This convergence of high-value transactions stems from three distinct, overlapping factors:
- Macroeconomic Predictability & FX Stabilisation: Central Bank of Kenya (CBK) policy interventions and currency stabilisation have provided foreign institutional investors with a much clearer framework for dividend repatriation, exit pricing, and valuation modelling.
- Private Equity Fund Life Cycle Maturation: A significant wave of private equity investments deployed across East Africa between 2014 and 2018 has reached maturity. PE sponsors are actively utilising public market listings and strategic trade sales to distribute to limited partners (LPs).
- Regulator Velocity & Deal Facilitation: Regulators, including the Competition Authority of Kenya (CAK) and the Capital Markets Authority (CMA), have streamlined transaction approval timelines, reducing execution risk in complex multi-jurisdictional M&A.
Actionable Steps to Sustain Capital Market Momentum
To transform this transient surge of capital into multi-year structural depth, market participants and policymakers should prioritise four key strategic interventions:
- Tax Policy Predictability: Frequent shifts in Capital Gains Tax (CGT), withholding taxes, and corporate levies disrupt long-term valuation models. Institutional capital requires a predictable, multi-year tax framework to make multi-decade commitments.
- Unlocking Domestic Institutional Capital: Local pension funds and SACCOs hold trillions of shillings, predominantly invested in sovereign paper. Regulatory incentives that allow these funds to allocate higher percentages to corporate debt, infrastructure funds, and equities will provide stable domestic liquidity.
- Accelerating State-Owned Enterprise (SOE) Privatisations: Executing primary listings of viable state-owned commercial entities on the NSE, rather than relying on direct bilateral government sales, will expand total market capitalisation and attract global benchmark indices.
- Harmonising Regional EAC Market Mechanics: Streamlining cross-border listing rules, settlement platforms, and regulatory approvals across the EAC will enable Nairobi to aggregate regional order flow seamlessly from Uganda, Tanzania, and Rwanda.
Conclusion & Outlook
The recent surge in high-profile capital market deals demonstrates that Kenya’s underlying economic fundamentals remain resilient. By combining corporate operational strength with policy predictability and market infrastructure reforms, Kenya can cement its position as the premier financial hub and investment destination in sub-Saharan Africa.